Commercial collections · B2B only · Nationwide
Another business owes you money. Sven and his team go get it.
Commercial (B2B) collections only. We do not collect consumer debt. No fee unless we collect.
- Powered by
- Collected for our clients $1 billion+
- Clients served since 2002 35,000+
- Average experience per collector 25+ years
- Dedicated freight collectors Section 7 · Title 49
-
Why the clock matters
An invoice does not age well. It just ages.
You did the work. You sent the invoice. Then it went quiet, and chasing it became somebody's part time job. Meanwhile the account slides right across the aging report, and every move to the right narrows what can still be done about it.
Memories fade. The person who signed the purchase order leaves. A debtor who has ignored you for four months has learned that ignoring you works. And every state puts a statute of limitations on the debt, with freight on an even shorter clock. When that window closes, the invoice is just paper.
- 0 to 30 In terms
- 31 to 60 Chased
- 61 to 90 Ignored
- 91 to 120 Going cold
- 120+ Write-off risk. Move on these first.
Don't take our word. Take theirs.
Endorsed by the trades
C2C Resources is the endorsed collections partner of trade associations across the country.


Who we collect for
The one truck operation and the billion dollar balance sheet.
C2C Resources has worked commercial accounts at every level since 2002. The same process, the same terms and the same collectors handle a three thousand dollar invoice and a three hundred thousand dollar one. What changes is the strategy, not the standard.
-
Small and mid-sized businesses
Owner-operators, family firms, contractors, single-truck carriers.
One unpaid invoice can be the difference between making payroll and not. You get the same collectors the large accounts get, and a straight read on whether your account is worth working before anything is placed.
-
Large and enterprise organizations
National manufacturers, distributors, enterprise service firms.
Credit departments place the accounts that are contested, out of region or legally complicated, in volume and to a process. The people who recommend the team by name are credit and collections directors at companies of exactly that size.
Hear them say it
How it works
Five steps. You know where you stand after the first.
-
Tell us what happened
How much you are owed, who owes it, how old it is and what has already been tried. A short conversation, not an onboarding process.
-
You get an honest read
Before you place anything, we review the account and tell you straight whether it is worth pursuing, how long it is likely to take and what it will take to recover. If we do not believe it can be collected, we tell you that up front, before you spend any more time on it.
-
Send the paperwork
The contract, the invoices, the proof of work. Whatever establishes that the debt is real and that it is owed to you.
-
A veteran collector works it
Someone who has worked your industry for decades. You get status updates and reporting throughout, so you always know where the account stands.
-
You get paid
We collect, and we pay you. Recovered money is remitted to you every week, and there is no fee unless we collect.
Industries
Collectors who already know how your industry pays.
The reason an account goes unpaid in freight is not the reason it goes unpaid in software, and the deadline that decides a construction claim does not exist in aviation. Accounts go to a collector who has worked your industry for decades.
-
Trucking and Transportation
Freight claims run on their own clock and their own law. We keep dedicated freight collectors who work Section 7 and Title 49 every day, so the claim is handled before the eighteen month window closes.
-
Construction Materials, Supplies and Heavy Equipment
Material and supply houses, heavy equipment sales and rentals, general contractors and subcontractors. Each has its own problems, and lien deadlines and pay-when-paid clauses decide what is collectable, so the order an account is worked in matters more here than almost anywhere.
-
SaaS, Software and Technology
Growing annual recurring revenue and holding churn down is the whole game. We recover the receivable while protecting your brand, your product and, where it is still worth keeping, the customer.
-
Aviation
Maintenance and repair, parts suppliers, FBOs and charter operators. When an aircraft is on the ground, getting it back in the air comes first and credit comes second. Knowing the industry, and the tools inside it, is what gets a difficult customer to pay.
-
Legal Services
E-discovery, court reporting and the other companies that serve attorneys, along with law firms and legal service providers. A third party keeps you out of the awkward conversation with a client you still need to work with.
-
Wholesale Goods and Manufacturing
Manufacturers, distributors and wholesalers selling to other businesses on terms. By the time a buyer stops paying the goods have already shipped, so the account has to be worked quickly and in the right order.
-
No fee unless we collect
Contingency, with no management fee and no paperwork fee. If nothing is recovered, you owe nothing.
-
Legal forwarding at no markup
Most agencies work an account for a week or two, hand it to legal, then raise the contingency rate or add a legal management fee. The rate does not change here and there is no management fee. You pay filing fees and court costs at cost. It stays a last resort.
-
Weekly remittances
Money that comes in goes out to you every week, so a recovery does not sit in someone else's account improving their cash flow instead of yours.
-
Domestic and international
Including overseas creditors owed by companies in the United States, where waiting for the statute to run is the most common and most expensive mistake.
-
We find out why they are not paying
A company that cannot pay and a company that will not pay need opposite approaches. Working out which one you are dealing with comes before anything else.
-
Status updates and reporting
You are told where the account stands without having to chase your own collection agency for an answer.
Powered by C2C Resources
The tools you get when you work with me.
-
Profit Maximizer
Free web based receivables software to minimize bad debt.
On c2cresources.com -
Infomax Collection System
The objective is to find out the truth about your customer’s financial situation.
On c2cresources.com -
Direct Communication
Clear, up-to-date and accurate status reports, telephone updates, regular emails and account access around the clock.
On c2cresources.com -
Licensed and Certified
Only partner with a licensed commercial collection agency.
On c2cresources.com -
Legal Forwarding
Do you believe in paying people for work they fail to do?
On c2cresources.com
Free tools
Professional grade instruments. Yours at no charge, courtesy of Sven.
Three diagnostic tools for CFOs, controllers and credit managers: how fast your cash moves, what your aged receivables are really worth, and where risk enters your order to cash process. Professional grade. No charge and no obligation.
DSO Calculator
Is your cash moving as fast as it should? Open the instrument Instrument 02 ComplimentaryAR Diagnostic
What are your aged accounts really worth? Open the instrument Instrument 03 ComplimentaryOrder to Cash Control Assessment
Find the risk before it becomes a forecast miss. Open the instrument
Who works your account
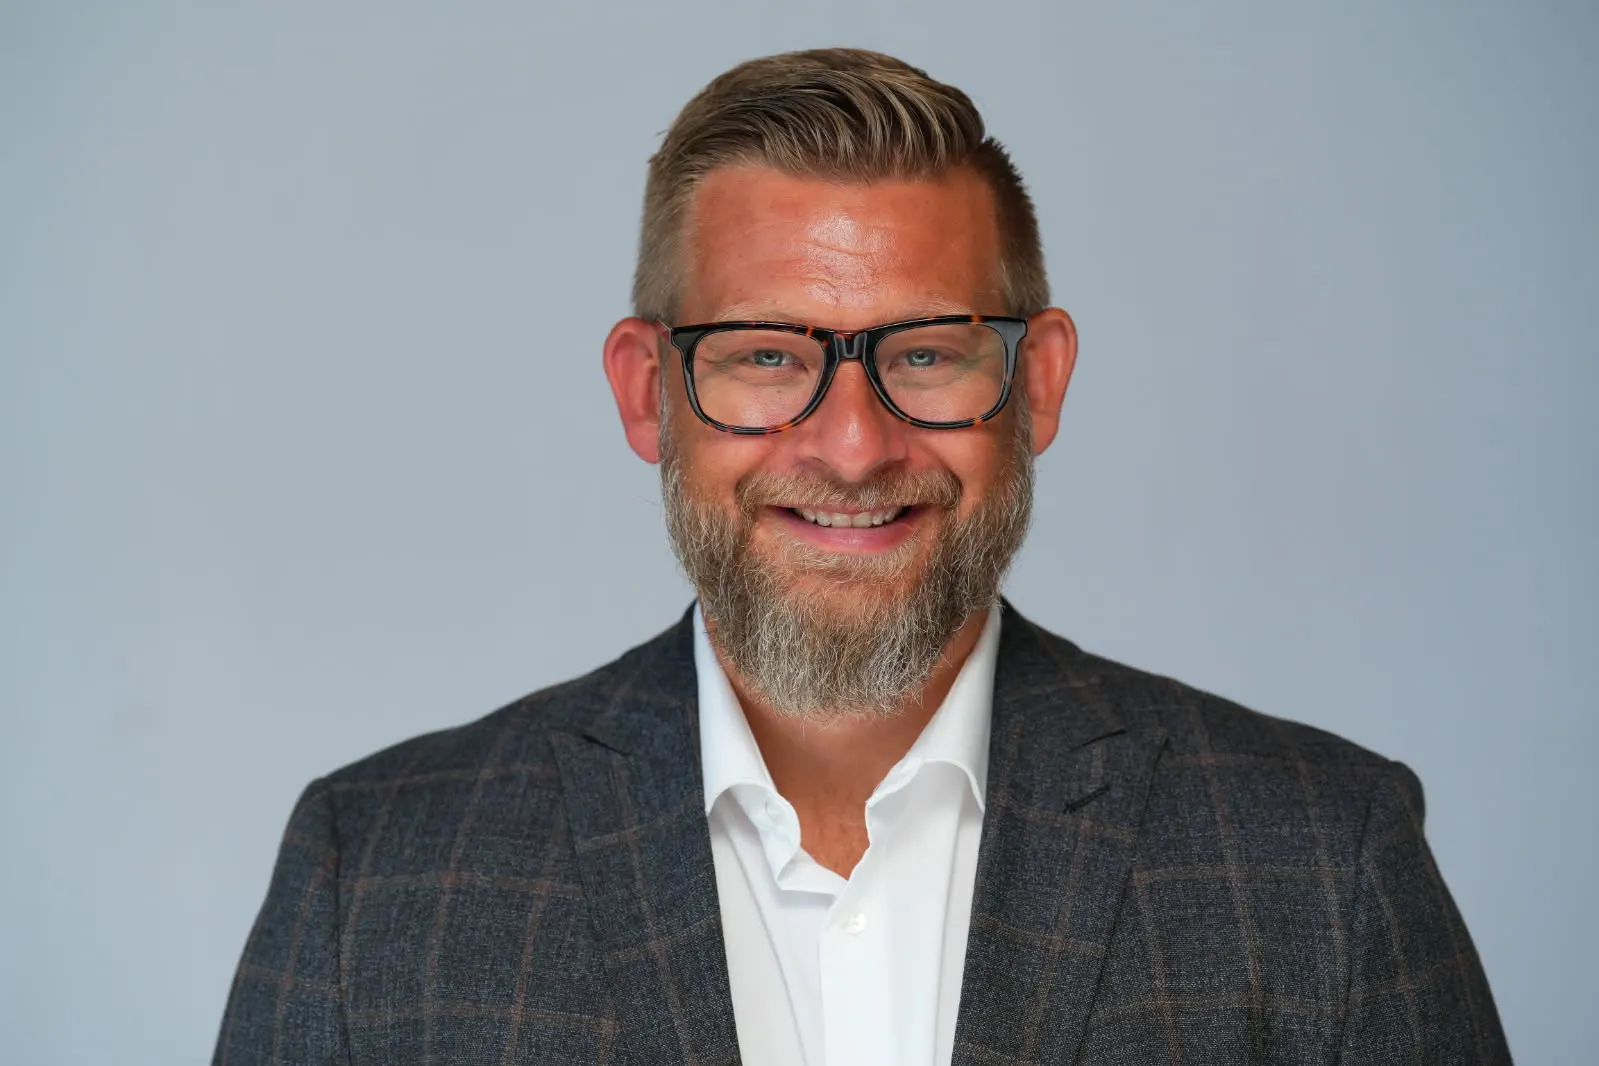
Sven leads it. A team of veteran collectors works it.
Your file goes to a collector who has spent decades recovering commercial receivables, not to a dialer pool and not to a script. Sven stays on the account. He works with CFOs, controllers, credit managers and owners on complex commercial delinquencies, across SaaS and technology, trucking and transportation, aviation, construction materials, supplies and heavy equipment, legal services, and wholesale goods and manufacturing.
Known professionally as The Guy That Gets You Paid, he also looks upstream at the credit decisions, the terms and the order to cash process, because collections is where a cash flow problem shows up, not where it starts.
In their words
Credit managers who placed accounts with Sven.
My company just started working with Sven and C2C Resources for collections and we saw results right away. He proved knowledgeable about our industry and the process and kept us informed throughout the entire time.
 George Nikitaras Corporate Controller and Finance Manager LinkedIn recommendation
I am constantly pleased with C2C's proficiency in obtaining funds from some of my most difficult customers. I highly recommend Sven and C2C for your recovery efforts.
 Jim Gray Director, Credit and Collections, Ash Grove Cement LinkedIn recommendation
I have worked with Sven for almost six years now. I would highly recommend working with Sven and his team at C2C.
 Melissa Scott Director, Epiq LinkedIn recommendation
I have worked with Sven at C2C Resources for several years. After all, he is The Guy That Gets You Paid.
 Alaina M. Worden, CCE Manager, Credit and Collections LinkedIn recommendation
Questions
Asked before every first account.
What kind of debt do you collect?
Commercial debt only. Every account we take is owed by one business to another business. We do not collect consumer debt, and we do not take accounts owed by individuals.
What does it cost?
It is contingency. There is no fee unless money is collected, no management fee and no paperwork fee. If the account is placed and nothing is recovered, you owe nothing.
Is there a minimum claim size?
Bring the account and you will get a straight answer on whether it is worth working before anything is placed.
How old can a past due invoice be before it is too late?
It depends on the state and on the kind of debt. Each state sets its own statute of limitations on a written contract and on an open account, and once it runs, the debt is no longer enforceable in court. Freight is its own case: claims under Section 7 and Title 49 run on an eighteen month clock rather than the state statute. The practical answer is that age is the single biggest factor in whether an account is collectable, so the older it is, the sooner it needs to move.
What do you need from me to start?
Whatever establishes that the debt is real and that it is owed to you. Usually the contract or the purchase order, the invoices, and proof that the work was done or the goods were delivered. Anything you already have from chasing it yourself helps too.
What happens if you cannot collect?
You owe nothing. That is the point of contingency. It is also why you get an honest read before the account is placed rather than after, including the times the honest read is that the account is not worth working.
Do you sue the debtor?
Only as a last resort, and legal forwarding costs you nothing extra. Most agencies work an account briefly, hand it to legal, then raise the contingency rate or add a legal management fee. The rate does not change here and there is no management fee. You pay the filing fees and court costs at cost. Suing also carries real downside: it opens you to countersuits you have to pay to defend, and the court system exists to decide questions of law, not to collect money.
Where do you collect?
Nationwide, and internationally. That includes overseas creditors owed by companies in the United States, where waiting too long to act is the most common and most expensive mistake.
Commercial (B2B) collections only. We do not collect consumer debt.
Let’s go get your money.
Bring the account. You get a straight answer on whether it is worth placing, what the timeline looks like and what it will take to get you paid.